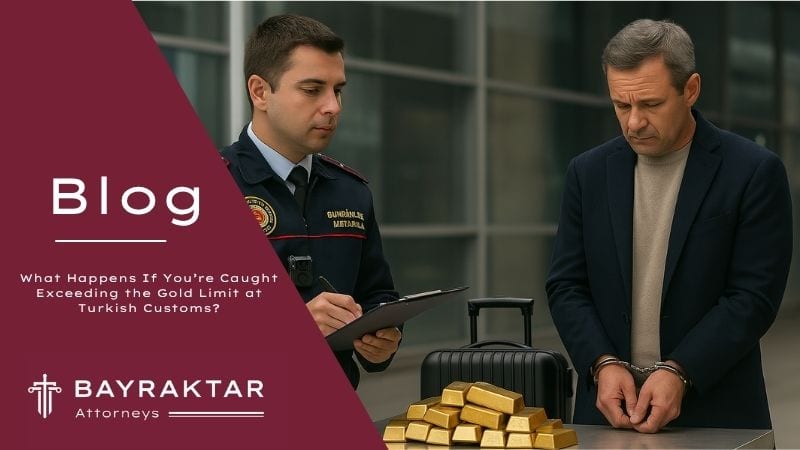
Quick answerPassengers may bring in and take out their own non commercial jewellery up to 15,000 US dollars; bars, coins and larger amounts must be declared. Undeclared commercial gold is smuggling under Article 3 of Law No. 5607: 1 to 5 years and up to 10,000 days' fine, or 2 to 5 years if hidden by deceptive means, heard by a designated asliye ceza court. Non commercial gold is taxed double (Article 235, Law No. 4458); unpermitted exits draw a fine of half to twice the value (Law No. 1567). Paying twice the customs value halves the penalty before indictment.
With gold prices at historic highs, more travellers pass through Istanbul, Antalya and other Turkish airports carrying jewellery, coins or small bars, and more of them are stopped at the green channel with gold they did not declare. The rules have also moved recently. Since 28 March 2025 the cash declaration threshold for Turkish Lira on departure is 185,000 Turkish Lira, and Law No. 7555 of 20 July 2025 rewrote the administrative fine for taking precious metals and other values in or out of the country without permission under the Law on the Protection of the Value of the Turkish Currency, Law No. 1567. Undeclared gold can lead to three different outcomes: an administrative fine and double customs taxes, a currency law fine decided by the public prosecutor, or a criminal smuggling case under the Anti-Smuggling Law, Law No. 5607. This article explains which rule applies when, what the penalties are, how seizure and confiscation work, which court hears the case, how effective repentance can reduce the sentence, and what a foreigner stopped at the airport should do in the first hours.
1. Three Sets of Rules That Overlap
Gold at the border sits at the meeting point of three bodies of law. The Customs Law, Law No. 4458, governs declaration, customs taxes and administrative penalties. Law No. 1567 and the Decision No. 32 on the Protection of the Value of the Turkish Currency, with its implementing Communiqué No. 2008-32/34, regulate the movement of precious metals, foreign currency and Turkish Lira across the border. Law No. 5607 turns certain breaches into criminal offences. Article 3(2) of Law No. 1567 itself states that its administrative fine for taking values in or out without permission applies only where the act is not an offence or misdemeanour under Law No. 5607. Identifying which of these routes the file is on is therefore the first question a lawyer asks, because it decides whether you face a fine, a prosecution, or both a criminal case and a tax dispute.
2. Declaration Rules for Gold When Entering and Leaving Türkiye
2.1 Personal Jewellery up to 15,000 US Dollars
Under Article 7 of Decision No. 32, as reflected in the customs administration's passenger instructions, passengers may bring into Türkiye and take out of Türkiye jewellery made of precious metals and stones that belongs to them, is not for commercial purposes and is worth no more than 15,000 US dollars in total. Taking out jewellery of a higher value requires that it was declared on entry or that you can document that it was bought in Türkiye. In practice, this means a declaration on arrival is your best protection for the return journey: a traveller who wears expensive family jewellery into the country without declaring it may have difficulty proving later that it was not bought in Türkiye.
2.2 Bars, Coins and Unwrought Gold
Bullion is treated differently from jewellery. The import of unwrought gold is regulated by Article 6 of Communiqué No. 2008-32/34: standard unwrought gold imported into Türkiye must have been produced by a refinery on the list published by Borsa İstanbul and carry its seal, name or emblem, and the import of non standard unwrought gold requires an assay report issued by the State Mint. These rules were written for trade imports, but they show why customs treats bars and ingots carried in hand luggage with suspicion. Bars, coins in quantity and investment gold that is not personal jewellery should always be declared at the red channel, with the purchase invoice, so that customs can decide whether they can be cleared as passenger goods or require a formal import.
2.3 Gold That Belongs to Someone Else
The jewellery allowance covers only the passenger's own items. Carrying jewellery or gold for a relative, a friend or a jeweller, even below 15,000 US dollars, falls outside the allowance and is exactly the kind of situation that customs officers treat as potentially commercial. Under Article 235(3) of Law No. 4458, goods a passenger presents as his or her own although they belong to someone else are also subject to the double tax rule described in section 5.
3. Declaration Rules for Cash
Gold cases often come with cash. Article 4(2) of Communiqué No. 2008-32/34 requires passengers leaving Türkiye with foreign currency exceeding 10,000 euros or its equivalent to declare it on the cash declaration form published by the Ministry of Trade, and Article 3(5) applies the same duty to Turkish Lira and Lira payment instruments exceeding 185,000 Turkish Lira. If no declaration, or a false or misleading one, is found, the cash is taken into custody, the case is reported as suspicious to the Financial Crimes Investigation Board (MASAK), and the public prosecutor is informed so that an administrative fine under Law No. 1567 can be considered.
| Item | Current Rule |
|---|
| Own jewellery, non commercial, up to 15,000 US dollars | May be brought in and taken out (Decision No. 32, Article 7) |
| Jewellery above 15,000 US dollars on departure | Allowed only if declared on entry or bought in Türkiye with proof |
| Bars, coins and investment gold | Declare at the red channel with invoices; trade imports of unwrought gold follow Article 6 of Communiqué No. 2008-32/34 |
| Foreign currency on departure above 10,000 euros | Cash declaration form required (Communiqué, Article 4(2)) |
| Turkish Lira on departure above 185,000 Turkish Lira | Cash declaration form required since 28 March 2025 (Communiqué, Article 3(5)) |
| Undeclared cash above the thresholds | Taken into custody, reported to MASAK and the prosecutor |
| Non commercial goods found contrary to the declaration | Customs taxes collected at double the rate (Law No. 4458, Article 235(3)) |
| Commercial goods found contrary to the declaration | Smuggling offence under Article 3 of Law No. 5607 (Article 6(4)) |
| Values taken in or out without permission, not smuggling | Administrative fine of half to twice the market value (Law No. 1567, Article 3(2)) |
4. When Undeclared Gold Becomes Smuggling Under Law No. 5607
4.1 Article 3 and the Penalty Ranges
Article 3(1) of Law No. 5607 punishes a person who brings goods into the country without subjecting them to customs procedures with 1 to 5 years' imprisonment and a judicial fine of up to 10,000 days; if the goods enter outside the customs gates, the penalty is increased by one third to one half. Article 3(2) punishes bringing goods in through deceptive acts and behaviour, so that customs taxes are wholly or partly unpaid, with 2 to 5 years' imprisonment and a judicial fine of up to 10,000 days. Hiding gold in a lining, a false bottom or inside other goods, or presenting false invoices, is the typical example of deceptive behaviour. Article 3(5) also punishes, with 1 to 3 years and up to 5,000 days, a person who did not take part in the smuggling but knowingly buys, sells, carries or stores smuggled goods for commercial purposes.
4.2 Commercial Character: The Dividing Line for Passengers
For travellers, the key provision is Article 6(4) of Law No. 5607. Where goods found on a passenger, in the luggage or in the vehicle contrary to the passenger's declaration are commercial in character, or their import or export is prohibited, Article 3 applies. Where they are not commercial, the case stays in the Customs Law: under Article 235(3) of Law No. 4458, goods outside the personal and gift allowances found contrary to the declaration are released after the customs taxes are paid at double the rate, and if the taxes are not paid the goods are treated as abandoned to customs. Whether gold is commercial is assessed from its quantity, form and value, from whether it is new and uniform (several identical bars, many unworn bangles with labels), from the passenger's travel pattern and from messages or documents found during the search. This assessment is often the heart of the defence.
4.3 Attempt, Value and Aggravating Circumstances
Three further rules shape the sentence. Under Article 3(22), the acts in Article 3 are punished as if completed even if they remained at the attempt stage, so being stopped at the customs desk does not reduce the penalty as it would under the general rules on attempt. Under Article 3(23), the penalty is increased by one half to one times where the value of the goods is excessive, reduced by up to one half where the value is light, with a further reduction where it is very light. Under Article 4, the penalty is doubled if the offence is committed within the activities of an organisation and increased by one half if three or more persons commit it together, and a separate penalty is imposed if forgery of a document is used. Couriers recruited to carry gold for others should know that these group provisions are often applied.
5. Administrative Consequences Under Law No. 4458 and Law No. 1567
When the case does not reach the criminal threshold, it still has a financial cost. The double tax rule in Article 235(3) of Law No. 4458 applies to non commercial undeclared goods. Separately, Article 3(2) of Law No. 1567, as amended by Law No. 7555 of 20 July 2025, provides that taking the values listed in Article 1 of that law, which expressly include precious metals and items made of them, out of or into the country without permission is punished, where it is not an offence or misdemeanour under Law No. 5607, with an administrative fine of half to twice the market value of the goods. If the act remains at the attempt stage the fine is halved, and a repetition within five years of the earlier decision becoming final doubles it. These fines are decided by the public prosecutor, not by customs, and are challenged under the general misdemeanour procedure. Note that Law No. 5607 is mainly built around bringing goods in; taking undeclared gold out of Türkiye is in most cases handled under Law No. 1567 unless the export of the specific goods is prohibited by law (Article 3(8) of Law No. 5607). Our article on objecting to administrative fines explains how such fines are challenged.
6. Seizure, Liquidation and Confiscation
Customs officers may search passengers, luggage and vehicles at customs gates when they suspect smuggled goods are being carried, and goods found are seized immediately (Article 9(2) of Law No. 5607). The seized gold is recorded in a report describing its quantity, type and distinguishing features and handed to the customs administration (Article 11). Ask for a copy of this report and check the weight, the number of pieces and the description carefully before signing it.
Goods that may be subject to confiscation cannot be returned to their owner while the case is pending. Under Article 16(1), a judge during the investigation, or the court during the trial, must decide on liquidation within six months of seizure, or within one month if the goods risk damage or loss of value; if no decision is taken in time, the goods are liquidated immediately. If the court later orders the return of liquidated goods, the sale price is paid to the owner with statutory interest (Article 16(2)). Confiscation follows the rules of the Turkish Penal Code, Law No. 5237, on the confiscation of goods and proceeds (Article 13), and even where no penalty is imposed because of effective repentance, confiscation of the gold itself remains possible (Article 13(2)). Our guide on confiscation under Turkish law covers the general principles.
7. The Court That Hears the Case
Under Article 17(2) of Law No. 5607, cases for offences under that law are heard by the asliye ceza mahkemesi, the general criminal court of first instance, specifically designated for smuggling cases by the Council of Judges and Prosecutors on the proposal of the Ministry of Justice. Where official document forgery is committed in connection with the smuggling, the heavy penal court has jurisdiction instead. The court sends a copy of the indictment to the customs administration, which may join the case as a participant (Article 18). How these courts operate, and what a hearing looks like, is explained in our guide to the asliye ceza court.
The criminal case does not decide the customs taxes. Assessments of duties and customs penalties are challenged first by objection to the customs administration within 15 days of notification (Article 242 of Law No. 4458) and then before the tax court, generally within 30 days under Article 7 of Law No. 2577. A single incident can therefore produce a criminal file and a tax file running in parallel, and the defence in one can affect the other.
8. Effective Repentance and Other Ways to Reduce the Outcome
8.1 Payment of Twice the Customs Value
Article 5(2) of Law No. 5607 gives the most practical route. A person who has committed one of the offences in Article 3, other than the import of goods prohibited by law under Article 3(7), and who shows effective repentance by paying to the State Treasury twice the customs value of the goods, receives a penalty reduced by one half if the payment is made before the investigation stage ends, and by one third if it is made during the trial before judgment. The public prosecutor must warn the suspect of this option during the investigation; if not, the judge must do so at trial. The reduction does not apply to repeat offenders or where the offence was committed within an organisation (Article 5(3)). The customs value means the CIF value plus the customs taxes (Article 2). Because the payment is large, the decision to pay should be made with a lawyer after the valuation is checked.
8.2 Informing on Others
Under Article 5(1), a participant who informs the authorities of the offence, the other perpetrators and where the goods are hidden before the authorities learn of it is not punished if the information leads to the arrest of the perpetrators or the seizure of the goods. A participant who helps reveal the full offence after the authorities have learned of it receives a penalty reduced by two thirds.
8.3 Deferral of the Verdict, Limitation and Conciliation
If the sentence finally imposed is two years or less, the court may defer the announcement of the verdict under Article 231 of the Code of Criminal Procedure, Law No. 5271, provided among other conditions that the damage to the public is fully remedied; the deferral does not prevent confiscation. Our article on the deferment of the announcement of the verdict explains the five year supervision period. For the basic offence in Article 3(1), whose upper limit is 5 years, the limitation period for prosecution is 8 years under Article 66 of Law No. 5237, although aggravated forms in the file are taken into account. Smuggling offences cannot be settled through conciliation, because Article 253(2) of Law No. 5271 requires an express provision in the special law and Law No. 5607 contains none.
9. What a Foreigner Stopped at the Airport Should Do
The first hours often decide the course of the file. These are the points we give clients:
- Stay calm and do not try to explain the gold away with an improvised story; inconsistent first statements are hard to correct later.
- Ask whether you are being treated as a suspect. If so, you have the right to remain silent and to a lawyer before giving a statement (Articles 147 and 149 of Law No. 5271).
- If you do not speak Turkish well, ask for an interpreter (Article 202 of Law No. 5271). Do not sign a statement or seizure report you do not understand.
- Check the seizure report: the number of items, the weight, the purity if stated and your declaration as recorded.
- Ask that your consulate be informed if you are taken into custody.
- Custody may not exceed 24 hours from apprehension, excluding up to 12 hours to bring you before the nearest judge (Article 91(1) of Law No. 5271). For in flagrante offences under Article 3 of Law No. 5607, a custody decision may even be taken by designated police chiefs (Article 91(4)(f)).
- Collect your purchase invoices, bank records, earlier customs declarations and photographs of family jewellery as soon as possible.
Most passengers in non organised cases are released after their statement, sometimes under judicial control, which can include a ban on leaving Türkiye. Our article on release under judicial control explains these measures. A foreigner should also keep immigration consequences in mind: Article 54 of the Law on Foreigners and International Protection, Law No. 6458, allows a removal decision for persons considered a threat to public order or who earn their living by illegitimate means, and these grounds are sometimes raised in smuggling files. Our criminal law services team regularly attends airport statements and can coordinate the immigration side.
10. Defence Strategy: What Is Usually Examined
Every file is different, but the same questions recur. Was the gold personal jewellery within the 15,000 US dollar allowance, so that no breach occurred at all? If not, was it commercial in character, which decides between Article 3 of Law No. 5607 and Article 235(3) of Law No. 4458? Was there deceptive behaviour, which moves the case from Article 3(1) to the heavier Article 3(2)? Is the valuation correct? The customs value drives the effective repentance payment and the value based increase or reduction under Article 3(23), so an expert report on weight, purity and market price on the date of the act is often worth challenging; see our guide on challenging an expert report. Was the search lawful and correctly recorded? And for exits, does the case belong under Law No. 1567 rather than Law No. 5607 at all? Investors who regularly move gold should also consider holding it in Türkiye instead; the options are described in our article on gold storage at Turkish banks for foreigners.
11. Frequently Asked Questions
11.1 How much gold jewellery can I bring into Türkiye without declaring it?
Your own non commercial jewellery up to a total value of 15,000 US dollars; above that, declare it on entry so that you can take it out again.
11.2 Do I have to declare gold bars or coins?
Yes, bars, coins and investment gold that are not personal jewellery should be declared at the red channel with the purchase invoices.
11.3 What is the penalty for gold smuggling in Türkiye?
Under Article 3(1) of Law No. 5607, 1 to 5 years' imprisonment and up to 10,000 days' judicial fine; with deceptive behaviour under Article 3(2), 2 to 5 years and up to 10,000 days.
11.4 Is every undeclared piece of gold a criminal offence?
No. If the gold is not commercial in character, the Customs Law applies and the customs taxes are collected at double the rate under Article 235(3) of Law No. 4458.
11.5 Is an attempt punished less severely?
No. Article 3(22) of Law No. 5607 punishes the attempt as if the offence had been completed.
11.6 What happens if I leave Türkiye with undeclared gold?
Unless the export is prohibited by law, the case is usually handled under Article 3(2) of Law No. 1567, with an administrative fine of half to twice the market value, halved if the act remained an attempt.
11.7 How much cash can I take out of Türkiye without a declaration?
Up to 10,000 euros or its equivalent in foreign currency and up to 185,000 Turkish Lira; above those amounts you must complete the cash declaration form.
11.8 Which court hears gold smuggling cases?
An asliye ceza court designated for smuggling cases by the Council of Judges and Prosecutors, or the heavy penal court if official document forgery is involved (Article 17(2) of Law No. 5607).
11.9 Can I get my seized gold back?
Only if the court orders its return; if it has already been liquidated, you receive the sale price with statutory interest, but confiscation is ordered where the offence is established.
11.10 What is effective repentance in a smuggling case?
Paying twice the customs value of the goods to the Treasury halves the penalty if paid before the investigation ends and reduces it by one third if paid before judgment (Article 5(2) of Law No. 5607).
11.11 Can the case be settled by conciliation with customs?
No. Conciliation under Article 253 of Law No. 5271 requires an express provision in the special law, and Law No. 5607 has none.
11.12 How long can I be held in custody at the airport?
Up to 24 hours from apprehension, plus up to 12 hours needed to bring you before the nearest judge, under Article 91 of Law No. 5271.
11.13 Can I be banned from leaving Türkiye?
Yes, a judge may impose judicial control including a ban on leaving the country while the investigation or trial continues.
11.14 Can a smuggling case affect my residence permit?
It can; a removal decision under Article 54 of Law No. 6458 is possible on public order grounds, so the criminal and immigration sides should be handled together.
11.15 Can I carry gold for a relative?
The jewellery allowance covers only your own items, so gold carried for someone else should be declared; otherwise it may be treated as commercial or subjected to double taxes.
12. Conclusion
Undeclared gold at Turkish customs can lead to double customs taxes under Law No. 4458, a fine of half to twice the market value under Law No. 1567, or a prosecution under Article 3 of Law No. 5607 with 1 to 5 years' imprisonment, or 2 to 5 years where deceptive behaviour is involved, before a designated asliye ceza court. Which route applies depends mainly on whether the gold is personal jewellery within the 15,000 US dollar allowance, whether it is commercial in character and whether it was hidden. Seizure is immediate, liquidation follows within six months, and effective repentance by paying twice the customs value can halve the sentence if used in time.
If you or a family member has been stopped with gold or cash at a Turkish airport, the statement, the seizure report and the decision on effective repentance all come early, so it is worth having a lawyer involved from the first day. To discuss the facts of your case, please contact our legal team.